Dr. Ahmad “Jordan” Al-Zu'Bi
Jordan Daily - As Governor Adel Al-Sharkas begins another five-year term, can Jordan’s financial and insurance institutions keep pace with risks changing faster than the rules designed to govern them?
Five years transform industries. Cars become computers on wheels. Insurance contracts move to smartphones. Medical disputes threaten access to care. Longer lives create obligations lasting decades.
But what happens when risks change faster than the institutions responsible for managing them?
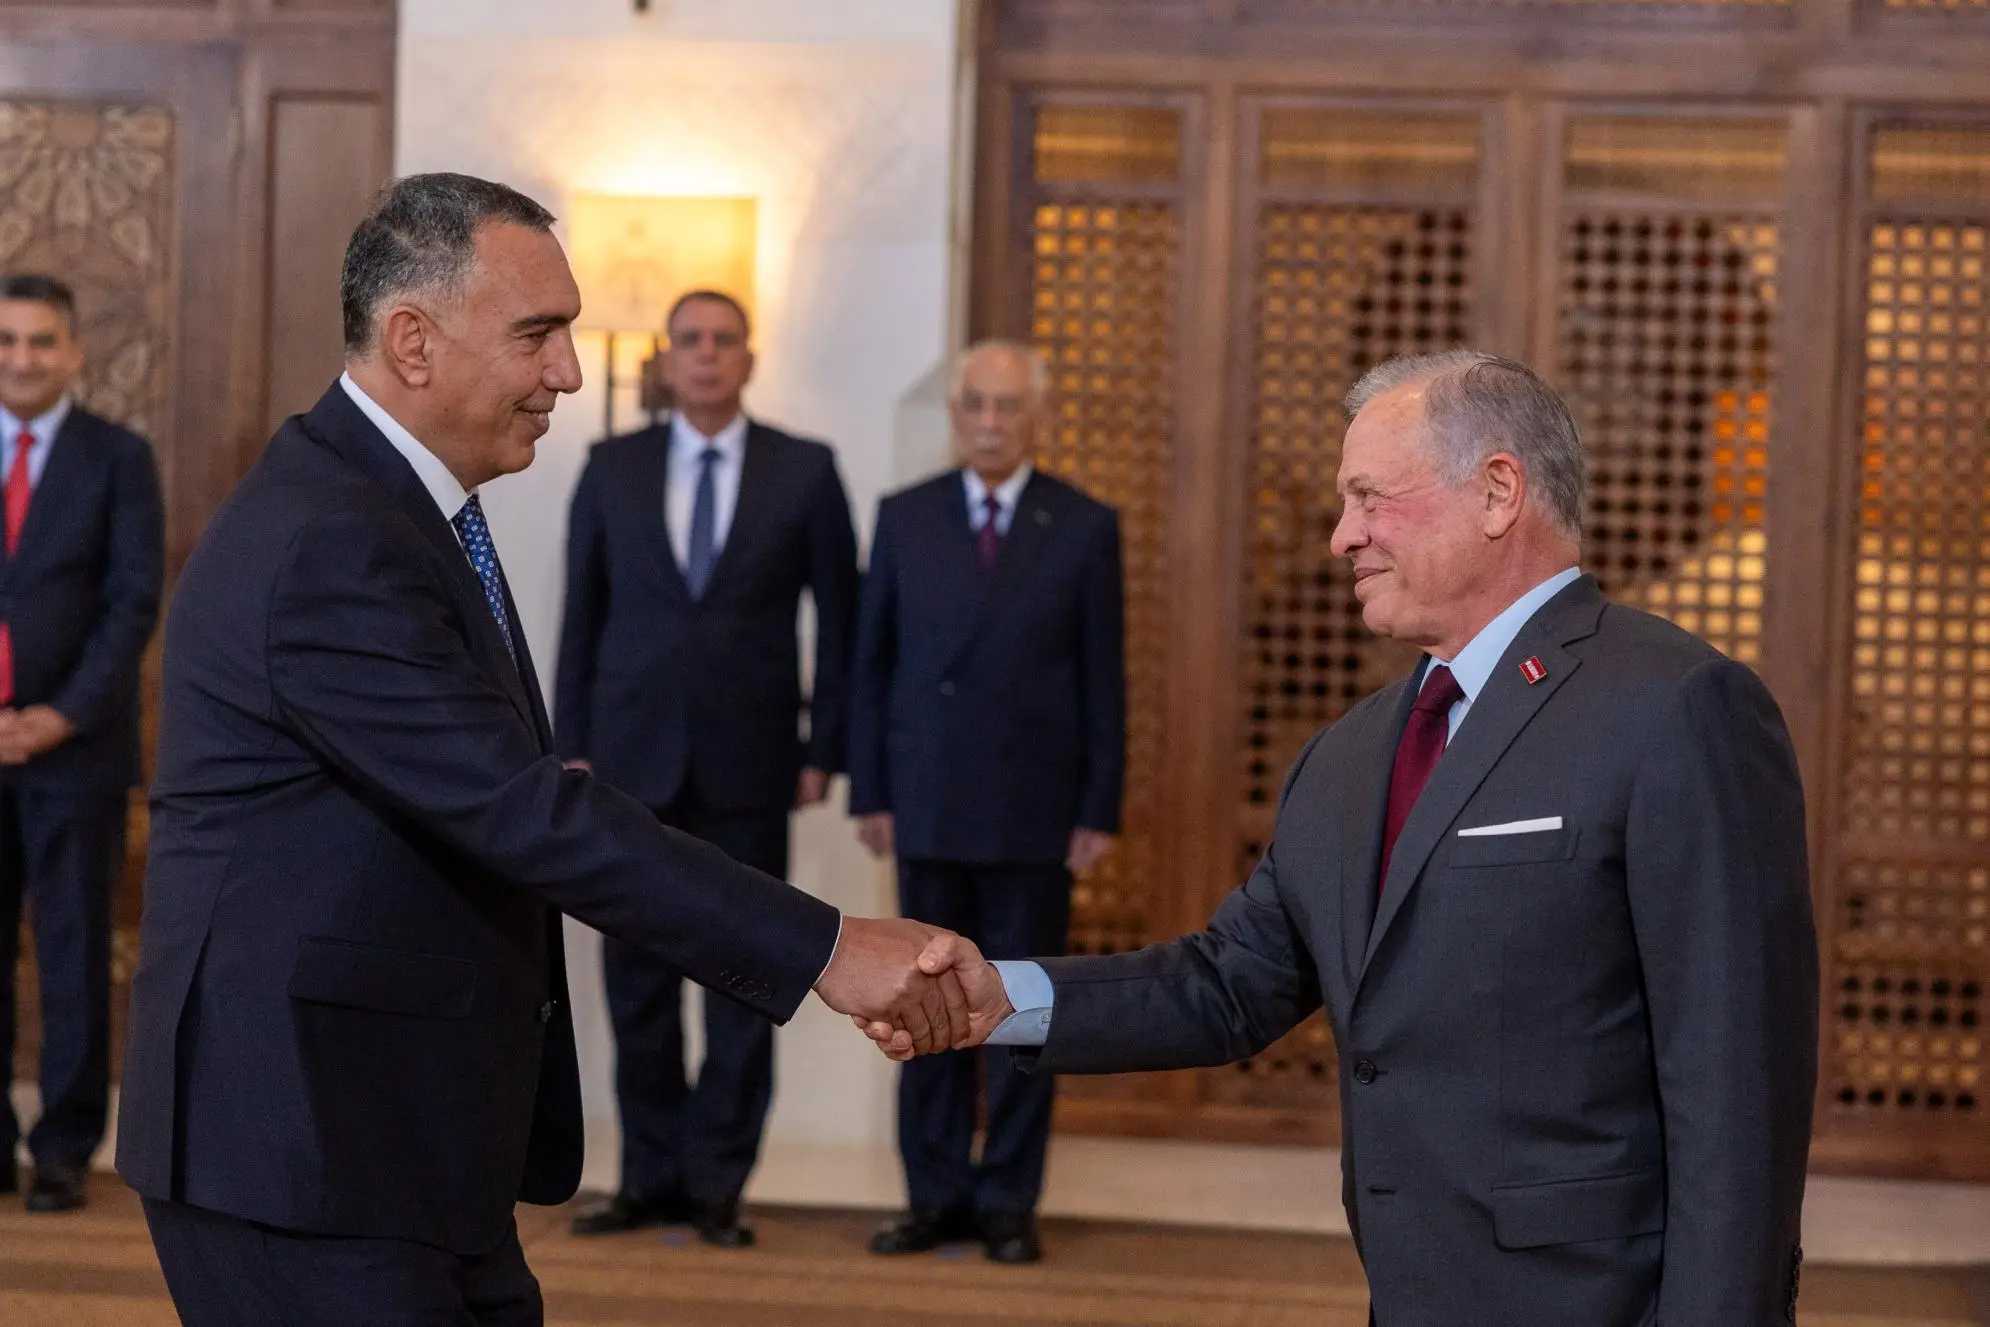
Last month, Dr. Adel Al-Sharkas was reappointed Governor of the Central Bank of Jordan for another five-year term, reflecting renewed confidence under His Majesty King Abdullah II. Jordan’s monetary and financial stability, alongside progress in financial inclusion, digital payments and insurance supervision, reflect the Governor’s leadership and the work of dedicated professionals.
For me, it is personal. Dr. Al-Sharkas was my professor. His recommendation helped me secure a highly competitive doctoral scholarship in risk management and insurance in the United States, shaping my professional journey. I congratulate him wholeheartedly, remembering the professor who recognized my potential before my career began.
To honor an economist who encouraged critical thinking, I keep asking difficult questions. Who bears risk? Who pays for it? And can insurance deliver the protection people have paid for?
When the Price Is Wrong, Everyone Pays
Should drivers with sharply different accident records pay nearly identical compulsory insurance premiums? Insurance pools risk, but prices should also reflect expected losses. As I have argued before, fairness does not mean sameness: different risks should not automatically carry the same price.
When safer drivers subsidize riskier drivers through similar premiums, cross-subsidization may weaken safe-driving incentives. Social support can be justified, but it should be transparent and targeted. Better claims data and risk classification help reconcile affordability with actuarial soundness.
Electric vehicles raise another challenge. Battery repairs can increase claims, but high premiums should be supported by evidence, not uncertainty alone. Reliable loss data, competitive repair markets and transparent pricing can help. Yet even fairly priced insurance means little if the promised protection cannot be used.
When Doctors and Insurers Fight, Patients Pay
Jordan’s dispute between doctors and insurance companies exposes the gap between having health insurance and obtaining healthcare. The Doctors’ Syndicate alleges breaches of medical-fee agreements; insurance representatives contest aspects of those claims and say alternative care remains available.
The Jordan Insurance Federation reports that 28 doctors among approximately 3,000 declined to treat insured patients, were removed from networks, and patients were referred elsewhere. This dispute is not entirely new: in November 2024, the Federation reported a similar episode involving 61 doctors. If disputes recur, are existing agreements resolving the underlying incentives or merely postponing another confrontation?
The Federation’s efforts to maintain access matter. But network adequacy is about more than numbers: patients need an appropriate specialist, within reasonable distance and waiting time, without unexpected charges. This matters especially for employees with private health coverage. American regulators use similar access measures; Jordan can adapt the principle.
Insurers must control medical inflation, verify claims and challenge unjustified charges. Doctors deserve payment for covered services. The economic problem arises when delayed payments or threatened withdrawal make confrontation a bargaining strategy, while patients bear the consequences.
The solution is practical. When an insurer questions part of a doctor’s bill, it should explain why, pay the accepted portion promptly and send the disputed amount for independent review through an existing agreed mechanism. Clear deadlines and consequences for unjustified withholding or overbilling would discourage repeated conflict. Meanwhile, covered treatment should continue; if a doctor leaves a network, the insurer should arrange genuinely accessible alternatives, especially for patients in ongoing care.
The objective is to make cooperation more rewarding than confrontation. Doctors gain predictable payment; insurers retain cost controls and stable networks; patients receive care; regulators gain reliable evidence; and government gains a stronger foundation for health reform. No agreement guarantees that everyone wins every dispute, but good rules can align their incentives.
Affordability without accessibility is incomplete insurance protection. This dispute merits a separate policy article and raises an even larger question: how can Jordan promise universal health coverage if the institutions delivering care cannot reliably work together?
Who Pays for a Longer Life?
Jordan’s proposed expansion toward universal health insurance should answer two questions: who is covered, and who pays? One model worth examining is Universal Workforce Health Insurance, anchored in the Social Security Corporation and delivered through multiple competing private insurers, with coordinated public oversight and insurance supervision by the Central Bank. This remains a proposal.
In such a multi-payer system, insurers should compete on service, efficiency and care outcomes, not on attracting only healthy workers. Risk-adjusted payments would compensate insurers appropriately for covering people with greater expected medical needs, while transparent financing would protect affordability.
Coverage must also mean more than enrollment: clearly defined benefits, dependable medical networks and credible actuarial forecasts are essential. Longer lives may mean longer pension obligations, more years managing chronic illness and greater long-term-care needs. Costs also depend on morbidity and medical innovation. Pension risk and healthcare risk sit on different institutional balance sheets but affect the same household. They demand coordinated planning across Social Security, health authorities, insurers and government.
Digital Insurance, AI and the Future of Liability
Jordan’s Insurance Contracts Law No. 11 of 2026 is progress. Implementation needs clearer guidance on digital policies, consent and signatures. When a policyholder accepts coverage on a smartphone, how can the insurer prove what was disclosed and agreed? Digital-signature safeguards should work with existing electronic-transactions law.
AI raises questions about underwriting fairness and accountability. Autonomous vehicles pose tangible ones: if a self-driving car crashes, who is liable, the driver, manufacturer or technology provider? Must a human remain alert? Can an occupant sleep? Will a driving licence still be necessary? Answers depend on automation levels. Jordan should prepare before those cases reach court. Cyber, energy and climate risks deserve attention too.
Every Regulation Has an Economic Consequence
Jordan should strengthen a dedicated insurance economics and regulatory impact assessment unit within the Central Bank’s insurance supervisory department. It can combine existing research capabilities with insurance economists, actuaries, data scientists and public-policy specialists.
Before major reforms, policymakers should ask: who benefits, who pays, how will behavior change, and what unintended consequences may follow? Motor pricing affects affordability; healthcare payment rules influence premiums; digital requirements can burden smaller insurers.
Every major reform deserves ex-ante and ex-post regulatory impact assessment: estimate economic and distributional effects before adoption, then measure results afterward. Evaluate incentives, competition, policyholder welfare, public spending and spillovers into other sectors, not just legal compliance.
The strongest regulator is not necessarily the one writing the most rules. It is the one that understands what those rules will change. Effective regulation also needs people who understand risk.
Teach Risk Early: Building Insurance and Risk Literacy
The Central Bank deserves significant credit for its financial literacy and inclusion initiatives. Jordan should build on them with age-specific insurance and risk-literacy programs.
Drawing on Stanford economist Annamaria Lusardi’s work, children aged 5–9 could learn uncertainty and shared protection through cartoons and games; ages 10–14 could explore probability and risk pooling; teenagers aged 15–18 could study fraud, responsibility and basic contracts. Young adults aged 19–25 need practical lessons on premiums, exclusions, deductibles, claims and medical networks. Older adults need guidance on health and retirement risks.
To educate the next generation, we must speak their language: animation, social media, short videos, trusted creators and interactive learning. Behavioral economics reminds us that information alone may not improve decisions, so programs should be evaluated. A ten-year-old learning about risk today may be buying insurance or joining the workforce ten years from now. Measure what that person understands, and whether the knowledge improves decisions.
The goal is not to create insurance economists. It is to raise a generation that understands uncertainty before its consequences become a personal crisis.
Five Years to Turn Regulation Into Protection
In my earlier Jordan Daily article, The New Era of Risk Needs a New Era of Regulation: What Jordan Can Learn from China, I explored why supervision must evolve as risks change. Here the question is more concrete: does regulation translate into protection policyholders can actually use?
I first studied with Dr. Al-Sharkas around 2009–2010. I remain proud to be his student. Today, as an insurance economist working on regulatory issues, we approach different institutional responsibilities through a shared intellectual language: the language of the New Era of Risk, grounded in economic evidence, public-policy consequences and regulatory spillovers.
The medical dispute, universal coverage and longevity merit separate articles I intend to pursue. Jordan has proved that it can preserve financial stability amid uncertainty. The next five years offer a chance to build something equally important: insurance protection Jordanians can trust when risk becomes reality.